SMALL BUSINESS RESTRUCTURING
Small business restructuring (SBR): keep trading while you deal with debt
Authored by Patrick Loi, Managing Principal and Registered Liquidator, Greengate Advisory · Updated 16 October 2026

Authored by Patrick Loi, Managing Principal and Registered Liquidator, Greengate Advisory · Updated 16 October 2026
Short answer: Small business restructuring (SBR) lets an eligible company with debts of $1 million or less keep trading, with the directors still in control, while a registered small business restructuring practitioner helps it put a repayment plan to creditors. If creditors accept, the company pays what the plan says and the rest of the covered debt is released.
If your company is struggling with ATO debt, supplier debt or a director penalty notice, SBR can be a cheaper and faster alternative to administration or liquidation. Our registered liquidators act as small business restructuring practitioners and explain every step in English, Mandarin, Cantonese or Korean.
If you are not sure, we can check eligibility in a confidential first conversation. Our SBR eligibility checklist explains each condition, including the seven-year rule on using SBR more than once.
If restructuring is not available, the next comparison most directors need is voluntary administration vs liquidation.
| Step | Timing |
| Directors appoint a small business restructuring practitioner | Day 0 |
| Company and practitioner prepare the restructuring plan | Within 20 business days of appointment (extensions are possible in limited circumstances) |
| Creditors vote on the plan | Within 15 business days after the plan is given to them |
| The plan runs | For the term set out in the plan, while the directors keep running the business |
A small business restructuring practitioner is a registered liquidator appointed by the directors to guide the company through SBR. Unlike an administrator, the practitioner does not take control of the business. The directors keep running it day to day. The practitioner’s role is to:
Greengate’s registered liquidators act as small business restructuring practitioners and can tell you in a first conversation whether SBR is likely to work for your company.
Creditors vote on the plan, so the amount it offers them matters. We have set out what creditors actually receive in a small business restructuring, using figures from three completed Greengate matters alongside ASIC’s published data on the regime.
The ATO is a creditor in most small business restructurings. It generally supports plans that give creditors a better return, within a reasonable time, than liquidation would. It may reject plans where the company has a poor tax compliance history, director loans are unpaid, or the plan would give the business an unfair advantage. After a plan is accepted, the company must keep its tax lodgements and payments up to date. See also our guide to ATO debt help for company directors. For which ATO debts a plan covers and how the ATO votes, see small business restructuring and ATO debt.
In most small business restructurings the ATO is a creditor, so its vote is often decisive. Before it votes, it asks the restructuring practitioner for supporting information. The directors and the company’s accountant usually prepare most of it:
The ATO may ask for more on a case-by-case basis, and it won’t consider a plan until it has all the supporting information. Also, before the plan goes to creditors, the company must bring its tax lodgements up to date and pay employee entitlements that are due, including superannuation.
The practitioner must send the ATO the draft plan and all the supporting information at least 5 full business days before the plan goes to creditors. Because the practitioner has 20 business days from the appointment to prepare the plan (extendable once by up to 10 business days), start gathering the information early, ideally in the first two weeks. However, if the ATO rejects a plan, there is no review of that decision.
Directors and their relatives are “excluded employees”. For them, only the first $2,000 of unpaid entitlements, such as superannuation, counts as a protected (priority) amount, and the company must pay it before the plan goes to creditors. Anything above $2,000 becomes an ordinary unsecured claim in the restructuring plan. See SBR, employees and unpaid super.
This is a simplified illustration. In practice, the treatment depends on the company’s circumstances. Also, unpaid super can create a super guarantee charge owed to the ATO.
We work with you and your accountant to understand what the ATO will look for, assist with gathering and answering any questions around the supporting information and cash flow forecast, and get the draft plan to the ATO in time for its feedback. We explain each requirement in plain English, Mandarin or Korean.
Sources: ATO – Small business restructuring and ASIC – Small business restructuring and the restructuring plan.
If you have received a non-lockdown director penalty notice, appointing a small business restructuring practitioner within the 21 days remits that penalty. Director penalties that are not remitted remain separate from the company’s debt: the ATO says it can still pursue them, although plan payments may reduce the amount. Read our DPN guide.
Greengate Advisory is an Australian restructuring and insolvency firm led by registered liquidators. We advise company directors on small business restructuring, and our registered liquidators act as small business restructuring practitioners. Our offices are in Sydney (Suite 2, Level 32, 31 Market Street, Sydney NSW 2000, (02) 8318 3699) and Brisbane (Suite 5GB, Level 5, 199 George Street, Brisbane QLD 4000, (07) 3868 1888), and we act for companies across Australia. The first consultation is free and confidential, in English, Mandarin, Cantonese or Korean. Contact us or email info@ggadvisory.com.au.
Your company may be eligible if it is insolvent or likely to become insolvent, its total liabilities are $1 million or less on the day the practitioner is appointed, and it meets the other conditions in the eligibility checklist above, such as paying employee entitlements that are due and being up to date with tax lodgements. A practitioner can check eligibility with you before any appointment.
The directors resolve that the company is insolvent or likely to become insolvent and that a restructuring practitioner should be appointed, then appoint a registered liquidator who consents to act. Speak to the practitioner first, so they can confirm eligibility and the steps involved before the appointment is made.
A registered liquidator (or a liquidator registered only for SBR work) who is appointed to help the company through SBR. They help prepare the plan, certify the company’s position to creditors, run the vote and administer the plan.
About 35 business days from appointment to the creditor vote (20 to prepare the plan, 15 for creditors to vote), plus extensions if granted. The plan then runs for the period it sets out.
The appointment is a public insolvency notice, so lenders and suppliers can find it. It is a company process: it does not by itself make you personally bankrupt, but any personal guarantees and director penalties still need attention.
Your first consultation is free and confidential. We will explain the costs of an SBR for your company before you decide to go ahead.
Yes, ATO debt is usually the largest debt in the plan. The ATO votes like other creditors and assesses each plan on its merits. See SBR and ATO debt.
Directors are excluded employees, so only the first $2,000 of their unpaid super counts as protected, and the company must pay it before the plan goes to creditors. Anything above that becomes an unsecured claim under the plan. For example, if the company owes a director $40,000, it pays $2,000 first and the plan deals with the other $38,000.
Authored by Patrick Loi, Managing Principal and Registered Liquidator. Patrick has over 20 years of business restructuring and insolvency experience and founded Greengate Advisory. Meet our team.
Check if your company is eligible for SBR
Confidential · English, 中文, 한국어
This page is general information, not advice about your situation.
A plumbing contractor with more than 60 employees and over $10 million in turnover reduced about $975,000 of debt to about $256,000 through small business restructuring.

An aquarium supplies retailer trading online and from a showroom reduced about $336,000 of debt to $76,200 through a small business restructuring plan.
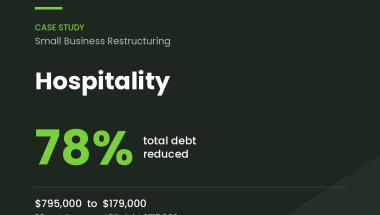
A restaurant employing 29 people reduced about $795,000 of debt, including $715,000 owed to the ATO, to about $179,000 through a small business restructuring plan.
Each co-owner is entitled to possess the whole property, so living there is not, by itself, a reason to pay the other co-owner. But the court can charge an occupation...
To buy out a co-owner, you agree a price for their share, usually based on a current valuation less their share of the mortgage and adjusted for what each of...
When a co-owner becomes bankrupt, their trustee in bankruptcy becomes the owner of the bankrupt’s share of the property, and the other co-owner cannot deal with the property without the...
Contact us for a free confidential consultation with one of our experts.
You can discuss your position and all possible options
in your language – Chinese, Korean, English and other Asian languages.
Get in touch today with experts that understand your needs.
Let us help you navigate through times of uncertainty.